FinBedrock Research · October 2026 · Baseline edition
Credit Card APR Index: Average APR by Issuer
By Nick Buinenko · Data as of · Updated monthly
Every variable APR is the Prime Rate plus a margin the bank picks. We split the two for every card we review, verified against issuer disclosures — by issuer, store vs bank, with the open data to download.
29.88 %
The average maximum APR across the 127 cards in the FinBedrock dataset is 29.88%, with the Prime Rate at 7.00%.
As of October 10, 2026
+4.25 pp
Store cards in the FinBedrock dataset carry a median maximum APR of 32.74%, 4.25 percentage points above the 28.49% median for bank cards (51 store cards, 76 bank cards).
As of October 10, 2026
+12.75 pp
Even at the low end of their APR ranges, store cards in the FinBedrock dataset carry a median APR of 32.24%, 12.75 percentage points above the 19.49% median for bank cards (39 of the 51 store cards have a single APR).
As of October 10, 2026
13 cards
All 13 highest-APR cards in the FinBedrock dataset (top 10, ties included) are store cards, with maximum APRs from 34.99% to 35.99%.
As of October 10, 2026
Every variable credit card APR is two numbers glued together: the Prime Rate, which is the same for every bank, and a margin, which each bank picks for itself. The Prime Rate gets the headlines. The margin is where cards actually differ, and it is the part you can do something about.
This index pulls those two pieces apart for the 127 cards FinBedrock reviews. Every APR in it was checked against the issuer’s own pricing disclosure or another tier-1 source, and each card’s margin is measured against the Prime Rate in effect on the day its APR was last confirmed. The data is as of October 10, 2026, with the Prime Rate at 7.00%.
One limit up front: this is the FinBedrock sample, not the whole US card market. It leans toward store cards (51 of 127) because store cards are a big part of what we review. Read the store-card numbers as “store cards we cover”, and see the methodology for exactly what is in and out.
What the data shows
These are observations only — numbers straight from the dataset, no interpretation. What they mean for your wallet comes further down.
- The average highest APR is 29.88%. The median is 28.74%. Across the whole sample, APRs run from 14.15% to 35.99%.
- The bank’s margin is most of the rate. At the top of their APR ranges, cards carry an average margin of 22.95 percentage points over Prime. The Prime Rate itself is 7.00%.
- Store cards cost more at both ends of the range. The median highest APR is 32.74% for store cards and 28.49% for bank cards. At the lowest APR the gap widens to 12.75 percentage points, because most store cards have a single rate with no low end to qualify for.
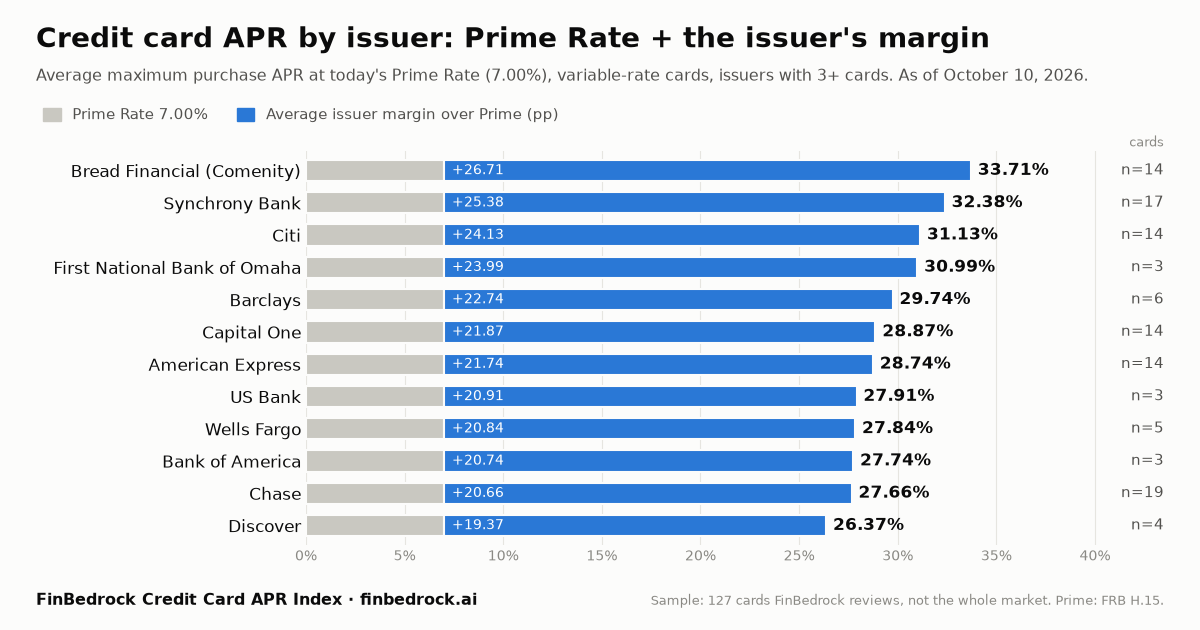
- Margins differ widely by issuer. Among issuers with 3+ cards, Bread Financial (Comenity) cards carry the widest average margin over Prime at the top of their APR ranges: 26.71 percentage points (14 cards), versus 19.37 percentage points for Discover (4 cards).
- The Prime move went straight through. After the Prime Rate rose to 7.00% on September 17, 2026, FinBedrock recorded APR increases matching the Prime move on 45 cards.
- Business cards in the sample run cheaper. The 10 business cards average a highest APR of 26.97%, against 30.13% for the 117 personal cards (personal here includes secured and student cards).
The chart below ranks every issuer with at least 3 cards in the sample. The grey part of each bar is the Prime Rate; the blue part is what that bank adds on top. Switch the view to “Margin over Prime” to see the banks ranked by their own pricing alone.
Prime Rate, 7.00% (same for every bank)
Issuer's average margin over Prime
How to read it: Each bar is today's Prime Rate (7.00%, grey) plus the issuer's average margin over Prime at the top of its APR range (blue), over its variable-rate cards (n). Totals use today's Prime Rate, so they can differ slightly from the observed averages in the table below. 33 of the 127 cards were last checked before the September 17, 2026 Prime Rate change; the full table shows every APR as verified.Average APR by issuer: Prime plus the bank's margin
Store cards are the clearest split in the data. We count a card as a store card when it carries a retailer’s brand — closed-loop cards that work only at that retailer, and Visa or Mastercard co-brands with a retailer. Airline and hotel co-brands, fintech cards (PayPal, Venmo, Apple, Bilt) and bank-branded cards count as bank cards.
Store cards are +4.25 percentage points higher at the top of the APR range. Store cards are +12.75 percentage points higher at the bottom of the APR range.Store cards vs bank cards
Highest APR (median)
Lowest APR (median)
The most expensive cards in the sample, ranked by highest APR (ties at the cut-off are included, so the list can run past 10):
Top 10 by highest APR, ties included (13 cards).The 13 most expensive cards are all store cards
The full table has every issuer with at least 3 cards in the sample, the average lowest and highest APR, the range, and the average margin over Prime. Month-over-month change starts with the next edition — this is the baseline.
Averages over each issuer's cards in the dataset; APRs as verified. Margin over Prime: average at the top of the APR range, variable-rate cards only.
10 issuers with fewer than 3 cards in the dataset are counted in the totals but not shown here.
Baseline edition: month-over-month changes start with the next edition.
Full table by issuer
Issuer
Cards
Avg highest APR
Avg lowest APR
APR range
Margin over Prime
Change vs last month
Bread Financial (Comenity)
15
33.79%
32.33%
19.49–35.99%
26.71 pp
—
First National Bank of Omaha
3
30.99%
30.99%
30.24–32.24%
23.99 pp
—
Synchrony Bank
17
32.28%
29.62%
18.74–34.99%
25.38 pp
—
Citi
14
31.06%
25.42%
16.99–33.49%
24.13 pp
—
Capital One
14
28.74%
23.74%
17.49–30.49%
21.87 pp
—
Barclays
6
29.62%
21.87%
19.49–33.24%
22.74 pp
—
Bank of America
3
27.74%
21.07%
17.74–27.74%
20.74 pp
—
Discover
4
26.24%
19.49%
16.49–26.49%
19.37 pp
—
American Express
14
28.72%
19.08%
16.99–28.74%
21.74 pp
—
Chase
19
27.66%
19.03%
16.99–28.49%
20.66 pp
—
Wells Fargo
5
27.74%
18.19%
16.74–28.49%
20.84 pp
—
US Bank
3
27.91%
17.82%
17.74–28.24%
20.91 pp
—
What this means for you
Everything above is data. This section is our interpretation of it.
Don’t carry a balance on a store card. If you pay in full every month, APR doesn’t matter — you pay no interest at all. If you don’t, the store-card numbers above are the most expensive place to do it. Their median highest APR of 32.74% is 4.25 percentage points above the bank-card median, and most store cards never offer a lower tier. Use them for the discount or the financing promo, then pay them off. Our store card vs regular credit card guide walks through when a store card still makes sense.
Watch “no interest if paid in full” promos. Many store cards sell deferred interest financing. Miss the deadline and you’re charged the interest that built up from the purchase date, at the card’s regular APR — for store cards in this index, a median of 32.74% at the top of the range. Our deferred interest guide explains the mechanics, and the deferred interest calculator shows the payment that keeps a promo at $0 and what missing it would cost.
Your rate will follow Prime — in both directions. After the September increase, FinBedrock recorded matching APR increases on 45 cards in the sample. When Prime falls, variable APRs fall by the same amount, but the bank’s margin stays where it is. A lower Prime Rate doesn’t make an expensive card cheap.
The margin is the number to shop on. Two cards can sit at the same Prime Rate and be very different deals. If you expect to carry a balance, look at the bottom of an issuer’s range and at whether you’re likely to qualify for it, or skip revolving debt altogether with a 0% intro APR or balance transfer card. If APR is new territory, start with what APR is and how card interest works.
Know who your bank is. Many store cards come from a handful of issuers. If yours says Comenity, our guide to Comenity Bank (Bread Financial) explains who you’re dealing with; for Synchrony cards, see what Synchrony Bank is. To compare cards across every issuer, browse the credit card hub.
Free to use with attribution (CC BY 4.0).
The CSV has one row per card, including cards of issuers too small for the table.
Download the data (CSV)
Download the chart (PNG)
Use this data
Source: FinBedrock Credit Card APR Index, October 2026 — finbedrock.ai/research/credit-card-apr-index/
Sample. The index covers the cards FinBedrock reviews: 131 cards on file, 127 in this edition. A card is left out when it has no purchase APR (a charge card) or when our automated validator has an open finding on its APR that has not been resolved yet — we would rather drop a card for a month than publish a number we can’t stand behind. The excluded cards are listed below. This is not a random sample of the US market: it leans toward store cards, so every figure describes the cards we cover. Where the APRs come from. Each card’s minimum and maximum purchase APR comes from the issuer’s pricing disclosure or cardholder agreement, or from another tier-1 source such as the CFPB credit card agreement database. A validator re-checks every card against the issuer on a rolling schedule. Card-confirmation dates in this edition run from July 12, 2026 to October 9, 2026. Prime Rate. We use the bank prime loan rate published by the Federal Reserve Board (H.15, FRED series DPRIME). It has been 7.00% since September 17, 2026. Margin over Prime. For each variable-rate card, margin = APR minus the Prime Rate in effect on that card’s as-of date. Measuring each card against its own date matters: 33 cards in this edition were last confirmed before the September 17, 2026 Prime change, and comparing their APRs with today’s Prime would understate their margin by the size of that move. Cards whose rate does not follow Prime (a fixed rate, or a rate at a legal ceiling) stay in every APR average but are left out of every margin average; they are listed below. Chart vs table. The bars in the main chart show today’s Prime Rate plus each issuer’s average margin. The table shows the APRs as they were verified. For issuers with cards confirmed before the last Prime change, the bar can differ slightly from the table’s observed average. Flat 35.99% store-card rates. Many Comenity-issued store cards list a single 35.99% APR that their disclosures describe as variable and based on the Prime Rate. We count them as variable, as disclosed. In practice the same 35.99% appears in agreements printed at different Prime Rates, so it behaves more like a ceiling than a Prime-plus-margin rate. Issuers. A card is assigned to the bank that issues it per its pricing disclosure, not to the brand on the front. Comenity Bank and Comenity Capital Bank are reported together as Bread Financial (Comenity). Issuer rows with fewer than 3 cards are hidden; those cards still count in every total, and n is always shown. Changes since the Prime move. We count APR changes recorded in FinBedrock’s card database since September 18, 2026. A card counts as matching the Prime move when every recorded change on it equals the +0.25 percentage point change in Prime. Dates are when FinBedrock recorded the change, not the issuer’s effective date. Updates. The index is updated monthly. Each edition is kept, so month-over-month changes can be shown from the second edition onward; this October 2026 edition is the baseline. Not in this edition: In the APR averages, but not in any margin average (the rate does not follow Prime):Methodology
How the index is built
Definitions
Excluded cards and rates not tied to Prime
Sources
Frequently Asked Questions
What is the average credit card APR right now?
Across the 127 cards in the FinBedrock dataset, the average highest APR is 29.88% and the median is 28.74%, as of October 10, 2026, with the Prime Rate at 7.00%. This is the sample of cards FinBedrock reviews, not the whole market, and it includes a large share of store cards.
Why do store cards have higher APRs than bank cards?
In this dataset, the median highest APR is 32.74% for store cards and 28.49% for bank cards. The bigger difference is at the low end: most store cards have one rate for everyone, so there is no lower tier to qualify for. Store cards are also easier to get approved for, and issuers price that risk into the rate. Our store card vs regular credit card guide covers the trade-offs.
What is the margin over Prime?
A variable APR is the Prime Rate plus a fixed number of percentage points the bank sets, called the margin. The Prime Rate is the same for every bank; the margin is what makes one card cheaper than another. In this dataset, the average margin at the top of the APR range is 22.95 percentage points.
Did credit card APRs go up when the Prime Rate rose?
Yes. The Prime Rate rose to 7.00% on September 17, 2026. Since then, FinBedrock has recorded APR increases that match the Prime move exactly on 45 cards. Variable-rate cards are contractually tied to Prime, so the increase passes straight through to cardholders.
How often is the APR Index updated?
Monthly. Each edition is kept, so from the second edition onward the table shows month-over-month changes for every issuer. The October 2026 edition is the baseline.
Can I use this data in my article?
Yes. The data and chart are free to use under a Creative Commons Attribution license (CC BY 4.0): credit “FinBedrock Credit Card APR Index” and link to this page. The full card-level CSV and the chart PNG are in the “Use this data” section above, with no sign-up required.

This content is for informational and educational purposes only and does not constitute financial advice. Credit card terms and APRs change — always verify current details directly with the issuer before applying.